Mortgage brokers
Websites and systems for mortgage brokers
Brokers run on their aggregator's tools: Mercury, MyCRM, Infynity, Salestrekker or similar, with ApplyOnline or Loanapp for lodgement. The gaps are at either end. Getting a borrower from a website visit to a complete fact-find, and showing clearly why each loan was recommended. ASIC's October 2026 review of best interests duty records made the second one hard to ignore.
Rather just ask someone? Talk to usIn short
A broker's website should turn a visit into a complete scenario: honest calculators, an online fact-find and a booking, feeding straight into the aggregator CRM. Behind it, records should show why each loan was recommended. ASIC's REP 840 in October 2026 criticised generic, boilerplate best-interests rationales, and said AI-assisted outputs must be explainable and documented.
General information about systems and processes, current as at November 2026. It isn't legal or compliance advice: check how the rules apply to your business with your regulator, professional body or adviser.
- What is the best interests duty?
- The legal obligation, since 1 January 2021, for mortgage brokers to act in the consumer's best interests and prioritise the consumer's interests when there's a conflict. In practice it means recording the client's needs and objectives, the options considered and why the recommended loan was chosen.
What actually works
Calculators that are honest earn trust
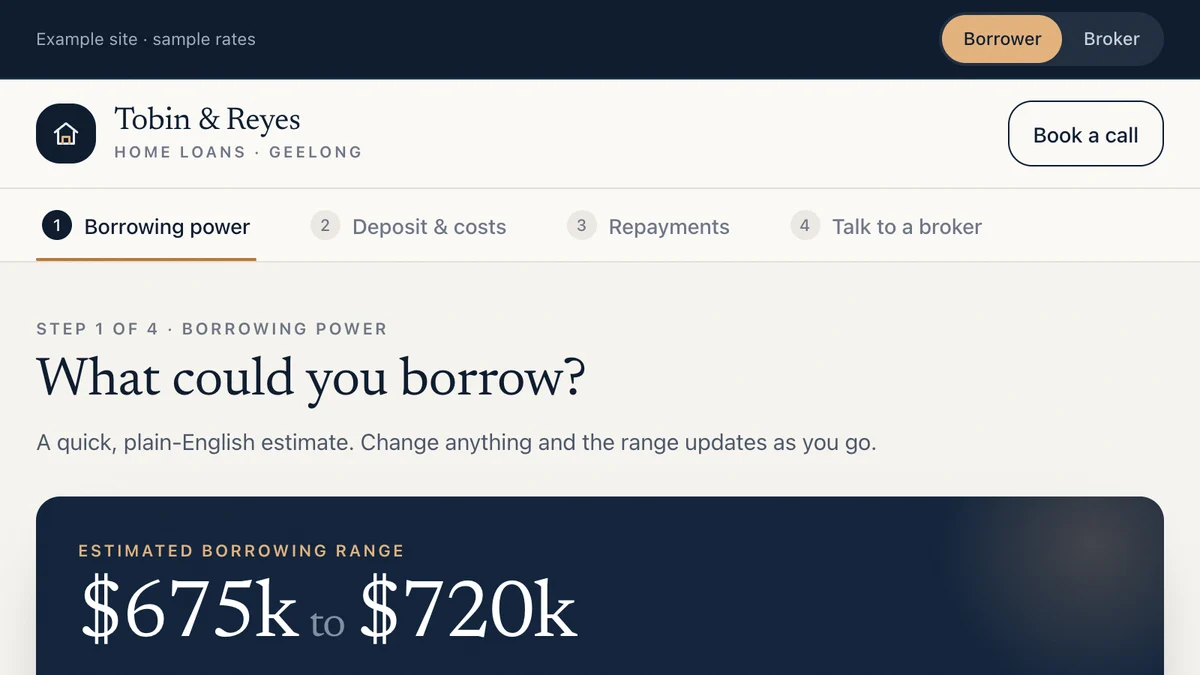
A borrowing-power estimate that shows its assumptions, and says it's an estimate, is more credible than a big number designed to capture a lead. Borrowers notice, and so do lenders and regulators.
Move the fact-find online
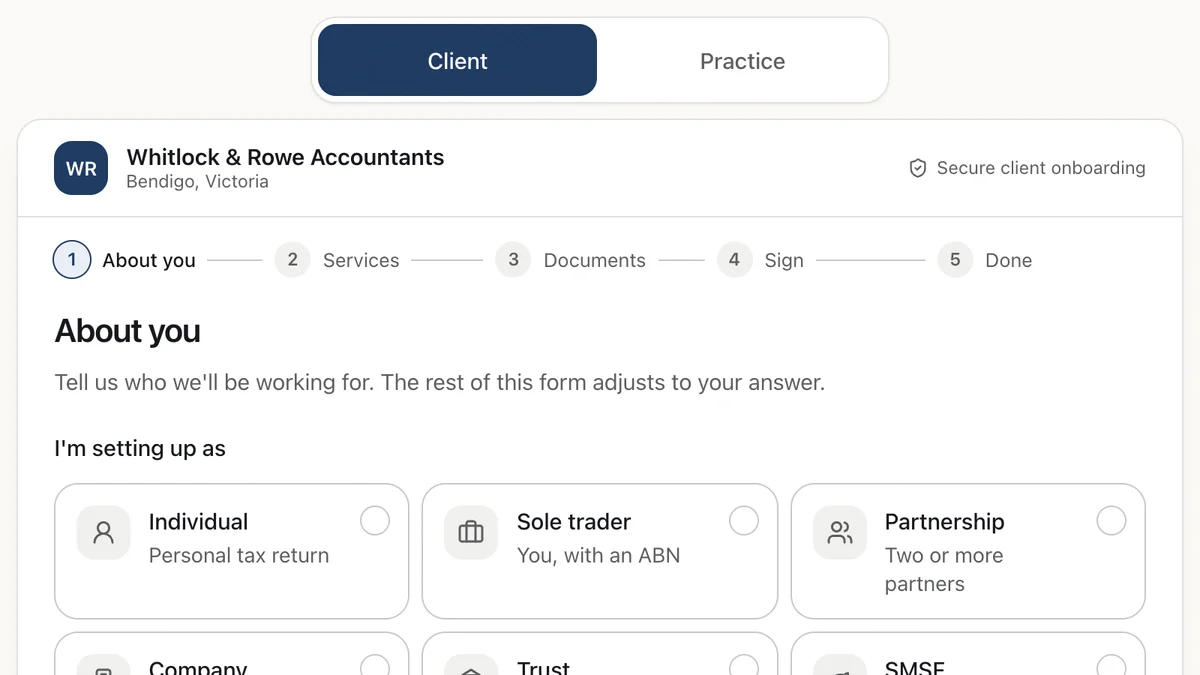
Income, expenses, assets, liabilities, goals and documents, collected on a phone in the borrower's own time, saves an hour of every first meeting and arrives more complete. It should flow into your CRM rather than becoming another PDF to re-type.
Records that explain the recommendation
ASIC's REP 840 reviewed 1,600 recommendations and found some brokers recommended much costlier loans without documented reasons. A good system prompts for the client's priorities and the comparison at the time, so the rationale is specific and complete.
Use AI carefully, and keep the record
AI can draft notes and summaries from the fact-find. ASIC has said outputs should be explainable and documented, and brokers stay responsible. Keep the AI's draft, the broker's edits and the final rationale together.
Get the licence details right
Credit advertising and prescribed documents must show the licence number in the required form, such as 'Australian credit licence 123456', not just 'ACL 123456'. Credit representatives show their own number and their licensee's. Put it in the site footer and on every calculator page.
Stay in touch after settlement
Past clients are the cheapest new loans: annual reviews, rate checks and fixed-rate expiry reminders, driven from your CRM's data. It needs to be helpful rather than spammy, and to respect opt-outs.
Broker website basics
Each one is either a lead or a compliance point.
- Licence or credit representative number shown in the required form
- Calculators state their assumptions and that they're estimates
- An online fact-find that flows into the CRM
- A booking link on every page
- A privacy policy that covers credit information and any AI tools
- Plain answers to first home buyer and refinance questions
Where we'd tell you otherwise
Your aggregator's CRM and website templates may already be enough, especially for a sole broker; configure them fully first. A custom site or fact-find earns its cost when you want to stand out locally, serve a niche such as self-employed or medical professionals, or join up tools your aggregator doesn't connect.
Tell us how your files move
Describe the software you run and where work gets typed twice, chased by phone or held up waiting on a client. We'll tell you what we'd do first, including when the answer is a setting in software you already pay for.
Common questions
Credit advertising and prescribed documents must show the Australian credit licence number in the form ASIC requires, and ASIC treats online marketing as advertising. Showing it in the site footer and on calculator pages is the simple, safe approach.
A report ASIC published on 13 October 2026 after reviewing about 1,600 home loan recommendations across eight aggregator groups. It found some brokers lacked documented reasons for recommending costlier loans, warned against generic rationales, and said AI-assisted outputs should be explainable and documented.
Often, depending on the CRM's integration options and your aggregator's rules. Where a direct integration isn't available, a structured export your team imports in one step still beats re-typing a PDF.
A broker with up to five staff can start on the Small Business Plan: $950 setup, then $95/month. Custom calculators, an online fact-find and CRM integration are quoted at a fixed price.
See it working
Software we'd build, running with a fictional business and sample data. Use it, then decide.
Also worth a look
- Real Estate Agency Websites That Win Listings
- Client Portals and Systems for Buyers' Agents
- AI for Real Estate Agents and Property Managers
- Holding client IDs and trust money? Security reviews for code, cloud and integrations
Last reviewed . General information, not legal advice. Prices are indicative Australian ranges, not quotes.